Soft credit review
What the purchase can support is reviewed on a soft credit pull, which leaves your personal and business credit untouched.
This takes a few seconds. Please keep this page open. You will go straight to your secure application as soon as it is ready.
Tell us about the purchase, and EBASCO Capital reviews it with lending partners that finance business acquisitions, including SBA 7(a) lenders. You can apply before the buying entity exists.
These are the numbers a lender runs the deal on.
Seller's Discretionary Earnings. A lender sizes the loan off this number.
A recent ownership change is underwritten differently.
Lenders generally want the lease term plus options to cover at least 10 years.
The buyer is underwritten separately from the business. This is your part, and we already have your name and contact details.
Lenders underwrite the business you are buying on its actual results. These are the two documents they always ask for.
Attach what you have. Nothing here holds up your prequalification, and you can add the rest later in your secure application.
The CIM, the LOI, bank statements, equipment lists, licences and anything else you already have on the business you are buying. No limit on how many.
PDF, JPG, PNG, Excel or Word, up to 100 MB per file. Bank statements, a personal financial statement and a debt schedule come later in the secure application.
Check the numbers. You can go back and change anything.
Your acquisition application is with EBASCO Capital's lending partners. Your secure portal is next: the rest of the application continues there, and lender responses arrive there as they come in.
The deal is described once and placed with lenders that write SBA 7(a) and conventional acquisition loans, so your time can go to due diligence.
What the purchase can support is reviewed on a soft credit pull, which leaves your personal and business credit untouched.
SBA and conventional options come back side by side, so they can be compared on rate, term and down payment.
Seller notes, standby debt and earnouts are treated as part of the capital stack from the first review.
Your portal shows where the file stands and what each lender needs next.
Describe the purchase in one application, with no cost and no obligation.
The deal is matched with lenders that finance acquisitions of this size.
Rate, amortization, down payment and guaranty requirements are laid out side by side.
The lender you select funds at closing together with your equity and any seller note.
Ownership changes hands with working capital in place for the first months.
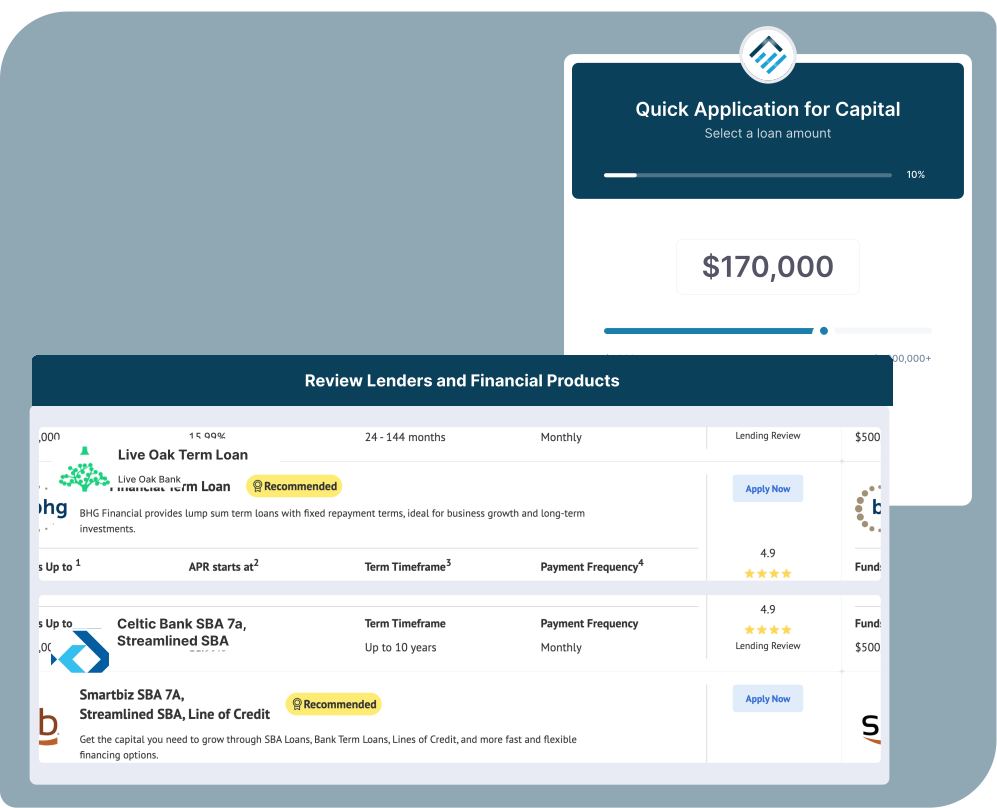
Each request is structured around the way the purchase will close, from the letter of intent to the funding.
Compare rates, terms and down payment requirements so your cash goes further.
Learn early what lenders will fund, so due diligence and underwriting can move at the same time.
Lenders that know the program, including the 10% down payment, standby seller notes and the owner-operator rule.
Apply with the real numbers, compare your options, and negotiate the purchase knowing what a lender will fund.